Introduction
AI startups span companies developing models and infrastructure, as well as businesses applying AI to specific tasks or industries. That range makes the label useful but broad: two companies described as AI startups may have very different products, customers, and routes to revenue.
For investors, founders, executives, and analysts, understanding the landscape means looking beyond the technology label. It helps clarify what a company builds, where it fits in the ecosystem, and what evidence would show that its product solves a real problem. For readers tracking AI markets, this distinction can help separate a technical capability from a repeatable product, and a compelling announcement from evidence of adoption. This guide maps the main sectors, explains common business models, and considers developments shaping the field in 2026.
It is an ecosystem guide, not a ranked list or investment recommendation. The categories are practical ways to organize AI startups, not a universal classification, and a company may work across several of them.
What counts as an AI startup?
There is no single universally accepted test for what counts as an AI startup. For this guide, the term covers young or developing businesses whose products or operations depend materially on AI, whether they build the underlying technology or use it to deliver a service.
One useful distinction is between AI-native companies, where AI is central to the product or technical offering, and AI-enabled businesses, where AI supports a broader product or service. Model developers and companies offering model access fit the first description. A software company using AI to add capabilities to an established workflow may fit the second. These are working descriptions, not formal or mutually exclusive categories.
Stanford’s 2025 AI Index groups AI activity across areas including infrastructure, data management, business operations, healthcare, finance, education, and autonomous vehicles. That broad industry taxonomy helps show why a single label can cover very different kinds of businesses, but it is not a definitive startup classification (Stanford HAI’s 2025 AI Index).
Important distinction: “AI-native” and “AI-enabled” describe how central AI is to a company’s offering. They are useful lenses, not standardized categories, and a company’s position can change as its products expand.
Key sectors where AI startups operate
AI startups can be grouped by what they build and whom they serve.
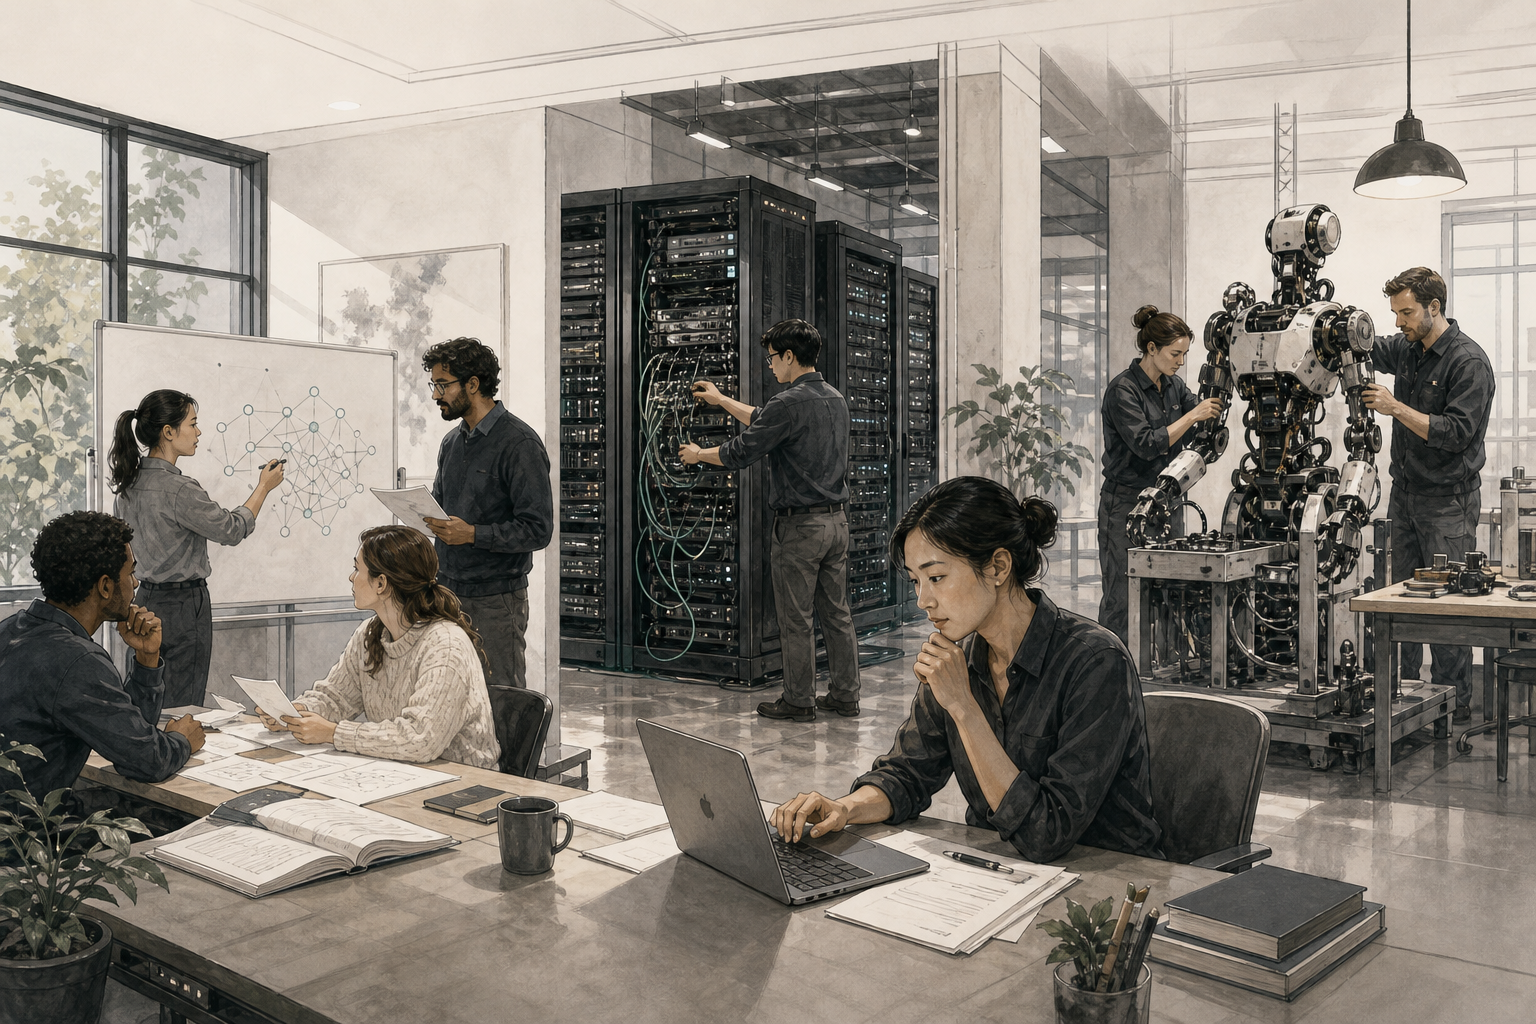
A practical map includes model development, infrastructure and tooling, applied software, and robotics or automation. These categories overlap: an application company may also build specialized models, while infrastructure supports products in multiple industries. Stanford’s 2025 AI Index provides a broader industry lens, listing areas such as cybersecurity, healthcare, finance, education, content, autonomous vehicles, and drones alongside infrastructure and data processing (report PDF).
| Sector | What companies build | Example verified in the reviewed sources | How it may connect to other sectors |
|---|---|---|---|
| Models and AI labs | General-purpose or specialized models, and ways to access them | OpenAI documents model and API access, including usage-based API pricing (pricing) | Models can power developer tools and applications |
| Infrastructure and tooling | Products for compute, data handling, deployment, evaluation, or development | No additional company example verified in the supplied sources | Supports model builders and application providers |
| Applied AI software | Products that use AI for business functions or industry tasks | No additional company example verified in the supplied sources | May combine models, data, and workflow software |
| Robotics and automation | Systems that apply AI to physical tasks or automated processes | No company example verified in the supplied sources | Can depend on models, sensors, hardware, and software |
Model developers may build general-purpose systems or adapt models for more specific tasks, while infrastructure and tooling providers support the work of building, testing, and deploying them. Applied software companies focus on using AI within a product or workflow for a particular user or industry. Robotics and automation extend AI into physical tasks, connecting software and models with sensors or hardware. These descriptions identify what a company offers; they do not imply that every startup performs all of these functions itself.
The table is a map, not a claim that every company belongs in only one sector. A useful way to classify a company is to ask what it sells directly and which parts of its product depend on AI. A business may sell an application while relying on an external model and infrastructure, or combine several layers in its own offering. The available evidence supports a broad range of activity, but does not verify named companies across every category. Treat the unfilled example cells as a research boundary, not proof that a sector lacks startups.
Funding figures also describe only part of the picture. Stanford’s 2025 AI Index reports 2,049 newly funded AI companies in 2024, an 8.4% increase from 2023. It counts newly funded companies, not all operating startups, and funding activity does not establish revenue, profitability, or adoption. It is a dated indicator of financing activity, not a measure of the whole ecosystem’s commercial performance.
Common business models for AI startups
AI startups can charge for access to software, models, or specialized services. Their pricing may combine a recurring fee with charges based on usage, but one company’s approach should not be treated as representative of the sector.
Subscriptions provide access to a product for a recurring fee. This model may suit an application customers use regularly, though the subscription price alone does not show how much it costs the provider to serve each account.
Usage-based pricing ties charges to consumption, such as API requests or tokens processed. OpenAI’s published API pricing lists separate input, cached-input, and output token rates. The company also states that API billing is separate from ChatGPT subscriptions, illustrating how a provider can offer both metered access and subscription products. Published prices do not reveal discounts, contract terms, operating costs, or margins, and they should not be assumed to represent other providers’ pricing (OpenAI API pricing; OpenAI developer pricing documentation).
Other possible models include enterprise licensing for access under negotiated terms, sales of infrastructure or developer tools, and application-specific products built around a particular task or workflow. Some companies may also provide implementation or support services. Outcome-linked fees are another possible approach, but the available evidence does not establish how common these models are across AI startups. Their presence and terms need to be checked company by company.
For founders and customers alike, the central question is whether revenue can sustainably cover delivery and acquisition costs. Depending on the product, relevant costs to examine may include compute and inference, data preparation or access, support, and customer acquisition. A price list cannot answer whether unit economics work: that requires evidence about actual usage, infrastructure requirements, contract terms, and the cost of serving customers. Treat the business model as a set of claims to validate, not as proof of profitability.
Emerging trends shaping AI startups in 2026
Several developments are shaping AI product design in 2026, but the evidence varies: some findings come from research or vendor-affiliated analysis, not independently verified customer deployments.
Smaller and specialized models are being explored alongside larger ones. A 2026 landscape digest describes systems that use smaller models and specialized neural networks for tasks such as perception, OCR, layout analysis, and retrieval, then pass condensed context to a larger model. Google’s account of a 2025 EMNLP study also describes small multimodal models for on-device interaction understanding in a specific intent-extraction task. These examples indicate research into specialization, not broad proof that small models are always cheaper, more private, or more capable. NVIDIA’s analysis presents lower latency, energy use, and infrastructure costs as potential advantages for some agent calls, while emphasizing heterogeneous systems that use multiple models. Those tradeoffs depend on the workload (2026 landscape digest; Google Research; NVIDIA Research).
Agents and workflow automation are moving beyond single-model prompting. A 2026 survey discusses tool use, retrieval, adaptation, and distillation of agents into smaller models. Clemson and NVIDIA describe a technical demonstration combining a fine-tuned model, video embeddings, retrieval, and agentic architecture for enterprise video search. These are research directions and demonstrations, not independent evidence of reliable, scaled customer use (IJCAI survey; Clemson and NVIDIA-affiliated work).
Multimodal systems are expanding the range of tasks under investigation. The available 2026 digest connects models that process video, audio, and visual information with research on vision-language-action capabilities. It also points to robotic manipulation, but does not establish dependable general-purpose robotics deployment or verified startup outcomes. Physical-world applications remain an area to monitor rather than a settled commercial capability.
Open and closed model ecosystems remain a tradeoff. Stanford HAI’s 2025 AI Index reports that open-weight models narrowed their gap with closed models from 8% to 1.7% on some benchmarks over one year. That is progress on selected measures, not universal parity. The same report documents a fall in the price of querying models at GPT-3.5-level MMLU performance from $20 to $0.07 per million tokens between November 2022 and October 2024. This specific comparison does not establish total costs for every workload. For startups, capability, control, deployment flexibility, provider dependence, and operating requirements all remain relevant dimensions, with no single direction established as inevitable (Stanford HAI 2025 AI Index).
How to evaluate an AI startup’s opportunity and challenges
A practical assessment starts with the customer problem, not the model. Who uses the product, what task does it improve, and what evidence shows that the improvement matters? Look for verified customer use and repeatable results, rather than treating a launch announcement or impressive demo as proof of adoption.
Next, examine what makes the company distinct. Its advantage might come from technology, distribution, integration into a consequential workflow, access to data, or expertise in a particular domain. Ask whether that advantage is demonstrated and durable, or whether the product relies on capabilities that customers can readily obtain elsewhere. Avoid assuming that a proprietary model is necessary, or that using an external model is automatically a weakness.
The technical questions depend on the product’s workload. Request task-specific reliability evidence, latency, hardware requirements, inference costs, privacy and data-handling practices, fallback behavior, and details about dependence on model providers. A system that performs well on a general benchmark may still behave differently in a customer’s workflow. Stanford HAI reported that the price of querying a model matching GPT-3.5-level performance on MMLU fell from $20 to $0.07 per million tokens between November 2022 and October 2024. That selected-model API comparison is not a measure of total operating cost or a guarantee of favorable startup economics (Stanford HAI’s 2025 AI Index).
Model choice also involves tradeoffs, not a universal winner. NVIDIA’s analysis argues that small models can offer latency, energy, and infrastructure advantages for some agent calls, while emphasizing workload dependence (NVIDIA research). Stanford HAI likewise reports a narrowing gap between open-weight and closed models on some benchmarks, not parity across all measures. Benchmark quality, privacy, reliability, and deployment cost should be checked separately.
For agent products, ask how tools are used, what happens when a step fails, and whether results hold outside a curated demonstration. A 2026 survey reviews research directions including tool use and smaller specialized models, but does not establish dependable commercial outcomes (IJCAI survey). Treat claims as claims until customer evidence and operating conditions can be verified.
What to watch next
Follow evidence that can distinguish durable products from short-lived demonstrations: verified customer use, repeat usage, workflow reliability, distribution, and economics under real workloads. For technical products, compare latency, infrastructure needs, and failure handling for the specific task rather than relying on a general benchmark.
Watch how companies balance model size, tool use, and serving design. Research and vendor-affiliated analyses discuss specialized models and heterogeneous agent systems, but these directions do not by themselves demonstrate broad adoption or dependable results. Robotics merits similar scrutiny: research capability is not proof of safe, reliable deployment at scale.
The useful question is not which trend will win, but which companies can show measurable value as their products meet real operating constraints. For ongoing developments, subscribe to The Deep View Newsletter for daily AI updates.
Conclusion
AI startups span infrastructure, models, applications, and systems that interact with the physical world. Their business models and operating needs differ, and many companies cross category boundaries. A useful assessment looks beyond trend labels to customer problems, product evidence, differentiation, and constraints such as reliability, compute, and data handling.
For investors, founders, and industry watchers, the strongest signals are specific and verifiable: customers using a product, performance on relevant tasks, and a credible explanation of how it fits into a workflow. These checks matter across categories, because a compelling demo alone does not establish repeat use, reliable performance, or a viable business. Keep tracking those developments with The Deep View Newsletter, which offers daily AI and technology updates.
Summary
AI startups range from model developers and infrastructure providers to applied software and robotics companies. Learn how these sectors overlap, how startups may charge for products and services, which trends are under investigation in 2026, and what evidence can help assess a company’s opportunity.